The past fortnight has shifted the market narrative slightly for Edinburgh prime property. The capital remains more resilient than the wider UK housing market, but the interest rate outlook has become less supportive. The Bank of England held its base rate at 3.75% on 17 September. However, the 6-3 vote was notably less comfortable than a straightforward hold.
For Edinburgh’s prime period home market, there are no immediate consequences. The latest local data shows prices above a year ago, homes moving within weeks for some properties and buyers paying above Home Report on average. Financing costs and economic uncertainty will keep buyers selective, particularly at the very top end.
Market Data at a Glance
Figures from the Office of National Statistics reinforce Edinburgh’s relative strength. The ONS’s July provisional figure puts Edinburgh’s average house price at £304,000, 4.0% higher than a year earlier, compared with 2.3% for Scotland. Registers of Scotland put Scotland’s annual increase at 2.3%, against 1.4% for the UK. These are broad-market figures rather than prime market measures, but they continue to show Edinburgh outperforming its national backdrop.
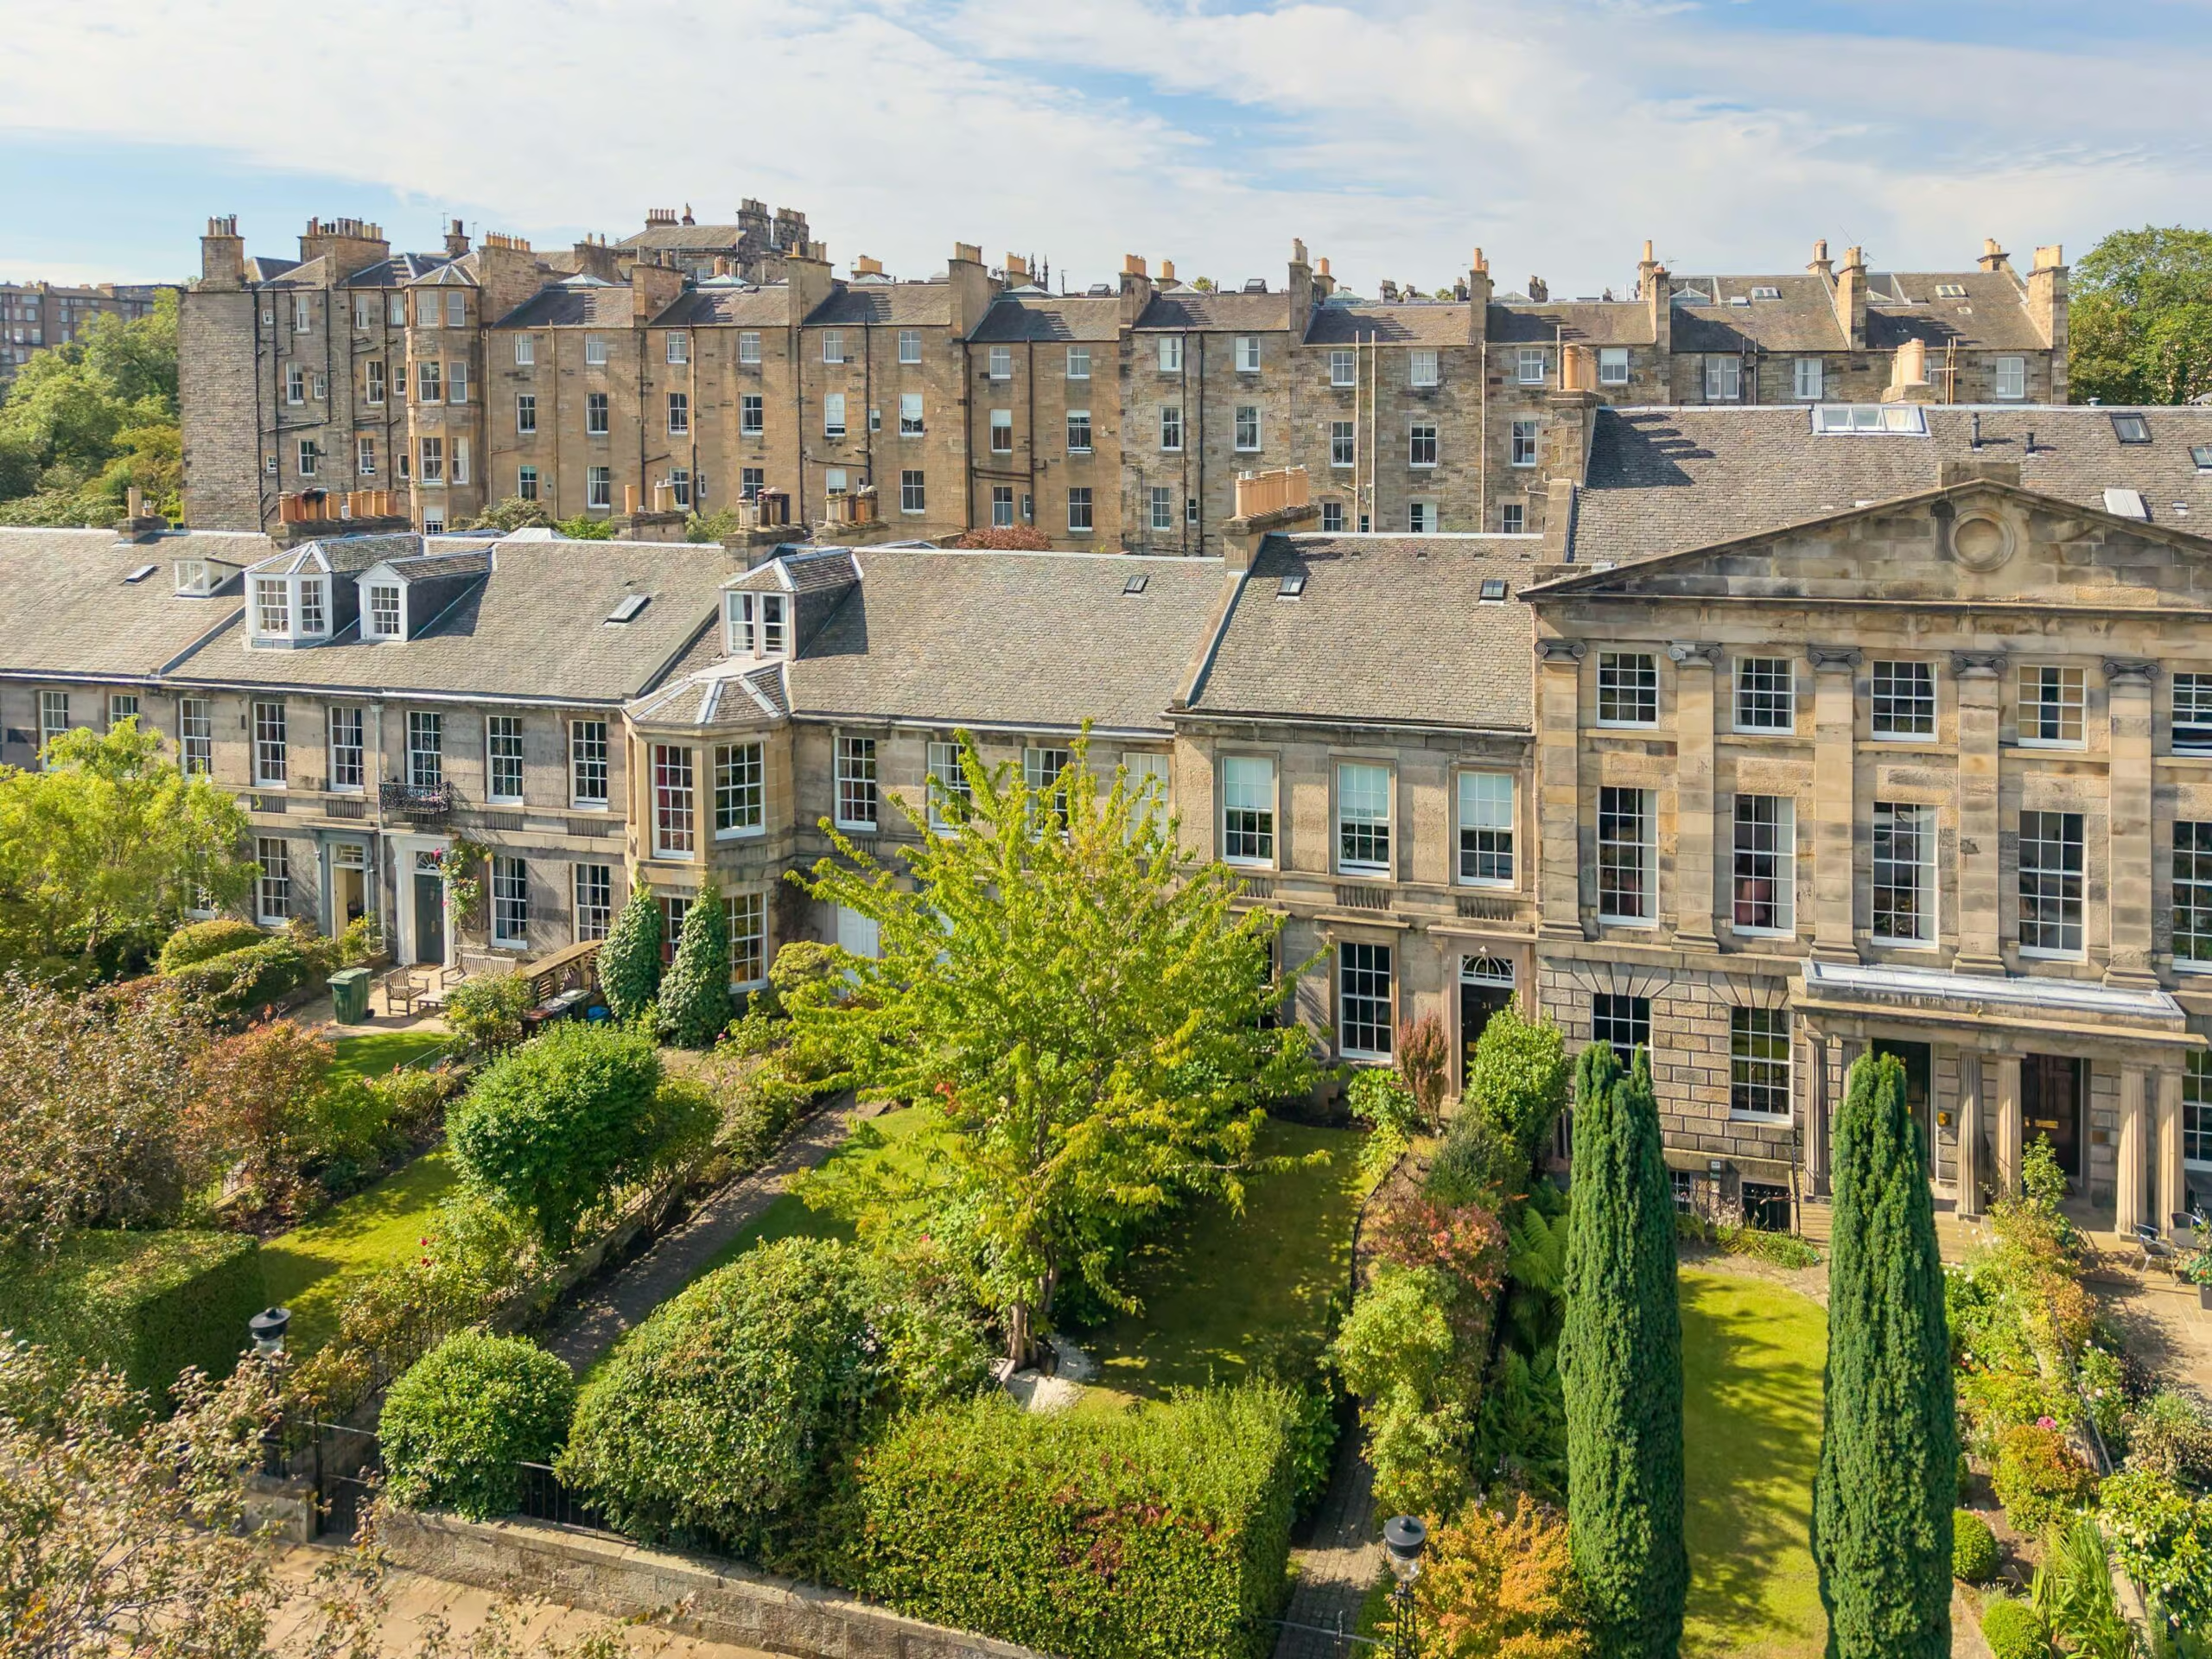
For period homes specifically, the significance is less about the headline average and more about relative scarcity. A well-located Georgian townhouse, Victorian villa or substantial family house is not readily substitutable, which means the best properties can still attract competition even while overall transaction volumes are more restrained.
Economic & Monetary Policy
The 17 September BoE decision is the most important development of the fortnight. Bank Rate remains at 3.75%, but the MPC voted 6-3, with three members preferring a rise to 4%. The Bank said inflation had risen to 3.1% in August and warned that persistent energy-price volatility could require higher rates if it becomes embedded in domestic inflation.
That is relevant to prime Edinburgh buyers even though many purchasers in this segment are less mortgage-dependent than the wider market. A higher-for-longer rate environment affects the opportunity cost of capital, mortgage affordability for leveraged buyers and, importantly, confidence around how much to commit to a purchase. The implication is not necessarily lower prime values; rather, it makes buyers more disciplined about price and condition.
The inflation rate published on 16 September provides the reason for that caution: CPI rose from 2.9% to 3.1% in August, with transport and particularly motor fuels making the largest contribution to the increase.
There are nevertheless some offsets. August retail sales rose 0.5% month-on-month and 2.4% year-on-year, while the BoE raised its estimate of third-quarter growth in its September assessment. The economy therefore continues to show resilience rather than a clear deterioration, although September’s business survey subsequently indicated slower growth and increased cost pressures.
Political & Financial Context
The 28 October Budget is now the principal political variable for the autumn property market. The date is confirmed by HM Treasury, and recent government borrowing figures have highlighted the limited fiscal headroom available to the Chancellor.
For Edinburgh’s prime market, potential changes to taxation and transaction costs are more relevant than broader housing policy. Until measures are announced, it is difficult to quantify any effect. The sensible market observation is that some discretionary buyers may prefer to transact before the Budget if they are already committed, while others may wait for greater clarity. That can create short-term hesitation without necessarily changing underlying demand.
Local Market Dynamics
Edinburgh continues to stand apart from the softer parts of the UK market. That is consistent with a market where buyers remain prepared to compete for appropriate property rather than one in which sellers are having to make widespread concessions.
At the same time, competition is not universal. Buyers are distinguishing more sharply between an exceptional property, an adequately priced property and one that requires substantial work or is priced ahead of the market. That distinction becomes particularly important above £750,000.
Buyer Behaviour
There is evidence of buyers returning to the market after the summer. Rightmove recorded a 5% increase in buyer demand during the first week of September, compared with an average 0.4% increase over the same period in the previous five years. Scotland’s increase was more modest at 1%, but the broader pattern suggests that the autumn market has begun with renewed engagement.
For Edinburgh prime buyers, however, renewed engagement should not be confused with indiscriminate buying. The strongest competition remains concentrated around scarce, turnkey or particularly well-located period homes.
Edinburgh has not responded to the national uncertainty with a broad-based correction. Instead, the market is becoming more differentiated. Buyers remain willing to pay above Home Report, but they appear increasingly unwilling to do so simply because a property is in a desirable postcode.
For sellers of prime period homes, this reinforces the value of presentation, specification and realistic pricing. For buyers, it creates a market in which patience can produce opportunities. Still, waiting for a wholesale fall in Edinburgh’s best stock may prove less straightforward.
Market Outlook
The outlook for the next few months is constructive but selective. The UK market is showing tentative signs of stabilisation: RICS reported that buyer enquiries, agreed sales and forward sales expectations all improved in August, although each remains in negative territory and RICS described the recovery as fragile.
Edinburgh enters that environment from a stronger position. The combination of annual price growth, selling times and sales above Home Report provides evidence of underlying demand. The question for the prime market is therefore less whether Edinburgh demand exists and more how much high-quality stock comes forward and at what price.
The main risks are now clearer: persistent energy-led inflation, the possibility of higher base rate, and uncertainty around the October Budget. The principal support remains Edinburgh’s underlying economic position and the limited supply of genuinely desirable period homes.
Guidance for Sellers & Buyers
For sellers, the current environment still supports bringing a high-quality Edinburgh period property to market, but pricing discipline matters. A strong property should benefit from autumn demand; an ambitious valuation without corresponding quality is more likely to encounter negotiation than it might have done in a more competitive market.
For buyers, there is no need to assume that every prime property will generate a bidding contest. The reduction in closing-date activity indicates greater selectivity. However, genuinely scarce houses in established prime locations remain a different proposition: if the property meets the brief and is correctly priced, delaying purely in anticipation of lower rates or a post-Budget opportunity carries its own risk.
Final Thoughts
Edinburgh’s prime period home market remains resilient. On the other hand, the Bank of England’s hold at 3.75% means the autumn market is likely to reward quality, scarcity and sensible pricing rather than indiscriminate optimism. A strategic approach is key to a successful sale. Would you like to discuss your options? Contact me, Fiona Vernon today by emailing [email protected] or phoning 07900 605674 now.
Pingback: Economic and mortgage updates